VA Loan vs Conventional Loan: Which Is Better for DFW Homebuyers in 2026?
Key Takeaways
- For most eligible veterans in DFW, a VA loan delivers superior long-term value: zero down payment, no monthly PMI, and interest rates typically 0.25–0.50% lower than conventional loans — saving tens of thousands over the life of the loan.
- The VA Funding Fee (2.15% for first-time use with no down payment) is a one-time cost that can be financed into the loan; over 10 years, PMI savings alone ($10,800–$58,200) typically exceed this fee — and disabled veterans are fully exempt.
- Conventional loans remain the right tool for investment properties, non-VA-approved condos, and second homes — and may be competitive for veterans with 20%+ down payments who want to preserve their VA entitlement for a future purchase.
- Texas-specific rules matter: Article XVI, Section 50 restricts cash-out refinances for both loan types (max 80% LTV, once per 12 months), and the VA eliminated its builder-ID requirement as of March 31, 2026, streamlining new construction financing for veterans.
- Trust Oasis Home Mortgages for expert VA and conventional loan guidance backed by 166+ five-star Google reviews and 20+ years of local DFW experience — visit Oasis Home Mortgages to start your home financing journey.
VA Loan vs Conventional Loan: Which Is Better for DFW Homebuyers?
For most eligible veterans in the DFW area, a VA loan offers superior financial benefits: zero down payment, no monthly mortgage insurance, and interest rates typically 0.25–0.50% lower than conventional loans. However, the best choice depends on your eligibility, property type, and financial goals. Conventional loans remain necessary for investment properties and non-VA-approved condos, and may appeal to borrowers with substantial down payments who want to preserve their VA entitlement for future use.
Understanding the key differences in costs, eligibility, and long-term value between these two loan types will help you make the right decision for your DFW home purchase.
Oasis Home Mortgage
Free Rate Quote — No Obligation, No Credit Check
Core Service Programs:
- Home Purchase Loans for first-time buyers, move-up buyers, Veterans, and luxury clientele across Texas
- Refinancing & Debt Consolidation for lower rates, cash-out refinances, and consolidating high-interest debt
- Private Money & Specialty Loans for self-employed borrowers, business owners, real estate investors, jumbo financing, and complex scenarios
Why Choose Oasis Home Mortgage:
- ✓ Trusted by customers with 166+ five-star Google reviews
- ✓ Led by Shane Campbell — 20+ years as a mortgage professional
- ✓ Based right in Trophy Club — a local presence, not a distant office park
- ✓ Borrower-education approach — loan options and compensation explained honestly
- ✓ Broad lender access for competitive rates on purchase and refinance loans
- ✓ Loan programs for every situation — FHA, VA, Conventional, Jumbo, and 2-1 Buydown
- ✓ Built on lasting client relationships, not one-and-done transactions
VA Loan Fundamentals: Program Overview and Core Benefits
The VA Home Loan Guaranty Program is administered by the U.S. Department of Veterans Affairs under 38 U.S.C. Chapter 37. Because the federal government guarantees a portion of each loan, lenders take on less risk — and that reduced risk flows directly to borrowers in the form of lower rates, no down payment requirement, and no monthly mortgage insurance.
Eligibility requires meeting one of the following service thresholds: 90 consecutive days of active duty during wartime, 181 days during peacetime, or six years in the National Guard or Reserves. Surviving spouses of service members who died in the line of duty or from a service-connected disability also qualify. Once eligible, veterans obtain a Certificate of Eligibility (COE) — which a VA-approved lender can often pull on your behalf — and they’re ready to use one of the most powerful mortgage benefits available.
One of the most underappreciated features: veterans with full entitlement face no VA-imposed loan limit. That means a zero-down purchase is possible even for higher-priced homes — highly relevant in markets like Trophy Club, where the median home price reached $716,000 as of mid-2026. The VA Funding Fee (2.15% for first-time users with no down payment; 1.50% with 5% down) is a one-time cost that can be rolled into the loan. Disabled veterans and Purple Heart recipients are exempt from this fee entirely. Explore VA loan eligibility requirements in detail to confirm your qualification status.
Feeling Overwhelmed by Loan Options?
You’re not alone. Many DFW homebuyers — especially first-time buyers and veterans — struggle to compare VA and conventional loans. The good news: understanding the core differences (down payment, PMI, interest rates) makes the decision much clearer.
Conventional Loan Fundamentals: Flexibility and Trade-offs
Conventional loans follow underwriting guidelines set by Fannie Mae and Freddie Mac. They’re available to any creditworthy borrower — no military service required — and they support primary residences, second homes, and investment properties, giving them a flexibility that VA loans simply cannot match.
The minimum credit score is 620, though most lenders prefer 640 or higher for optimal pricing. Down payment options range from 3% through Fannie Mae’s HomeReady or Freddie Mac’s Home Possible programs, up to 20% or more to eliminate Private Mortgage Insurance (PMI). That PMI cost is significant: on a $400,000 loan with 5% down, PMI runs $95–$475 per month depending on your credit score and lender. It automatically cancels when your loan balance reaches 78% of the original purchase price under the Homeowners Protection Act — but until then, it’s a recurring expense VA borrowers never pay. Review the full range of conventional mortgage options to understand which program fits your down payment strategy.
Interest rates on conventional loans run 0.25–0.50% higher than VA rates on average, according to HMDA data (NewDay USA, 2026). That gap compounds meaningfully over a 30-year term. Conventional loans also aren’t assumable — a notable disadvantage compared to VA loans, which a qualified buyer can take over at the original rate.
Head-to-Head Cost Comparison: VA vs Conventional Over 5, 10, and 30 Years
Pro Tip: Run the Numbers for Your Situation
Use an online mortgage calculator to compare total costs — principal, interest, PMI, and funding fee — for both VA and conventional loans with your expected down payment and credit score. This personalized comparison often reveals savings of $10,000–$50,000+ over 10 years for VA-eligible borrowers.
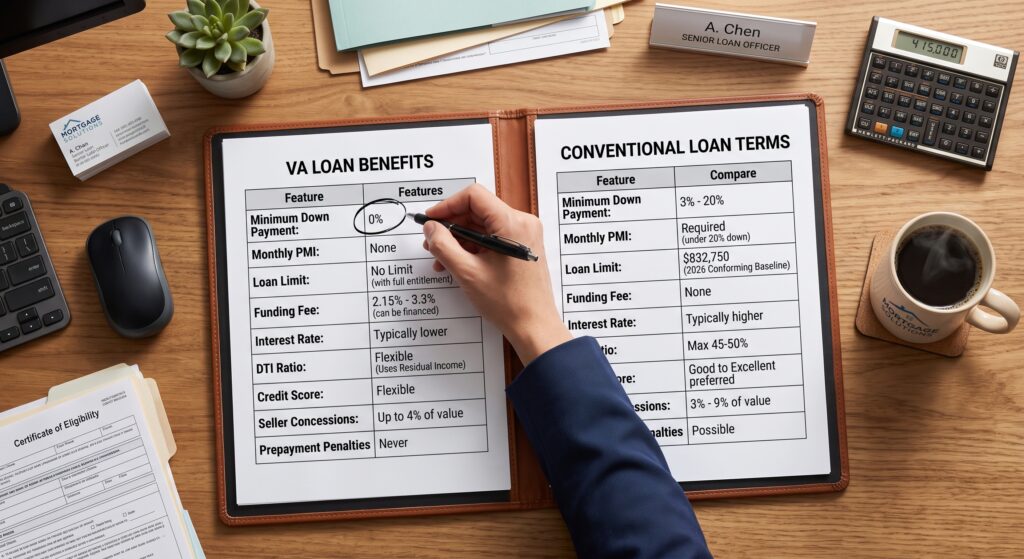
| Feature | VA Loan | Conventional Loan |
|---|---|---|
| Down Payment | 0% (full entitlement) | 3%–20%+ (PMI required under 20%) |
| Monthly Mortgage Insurance | None | $90–$485/mo on a $400K loan with <20% down |
| Interest Rate Advantage | 0.25–0.50% lower than conventional | Baseline market rate |
| One-Time Funding Fee | 2.15% (first use, 0% down); exempt for disabled vets | None (but origination fees apply) |
| 10-Year PMI Savings | $10,800–$58,200 vs. conventional | PMI paid until 78% LTV reached |
| 30-Year Interest Savings (0.25% rate gap) | ~$50,000 on a $400K loan | Higher total interest paid |
| Jumbo Purchase (above conforming limit) | 0% down with full entitlement | 10–20%+ down required |
| Assumability | Yes — any qualified buyer | Generally not assumable |
| Property Types | Primary residence only; VA-approved condos | Primary, second home, investment property |
For most VA-eligible buyers in DFW, the math strongly favors the VA loan — especially in Trophy Club, Southlake, and Westlake, where home prices frequently exceed the conforming loan baseline. A veteran purchasing a $700,000 home with zero down and no PMI versus a conventional buyer putting 10% down and paying PMI is looking at a dramatically different monthly payment and total cost picture. If you’re considering a larger purchase, also review jumbo loan financing options to understand how VA and conventional jumbo products compare.
Top VA and Conventional Lenders in DFW: Compared and Reviewed
Beware of Outdated Seller Perceptions
Some real estate agents still believe VA loans lead to longer closings or stricter appraisals. While VA appraisals do focus on property safety (Minimum Property Requirements), recent regulatory changes and improved lender processes have streamlined VA closings. Don’t let outdated myths discourage you from using your VA benefit.
Any lender originating VA loans in Texas must hold NMLS licensure and carry VA Automatic Authority or Prior Approval status. You can verify both at NMLS Consumer Access. Beyond credentials, what separates lenders is local knowledge, transparency on fees, and responsiveness — especially in a competitive market where closing timelines matter.
Oasis Home Mortgages
Located at 7 Greenbriar Ct, Trophy Club, TX 76262, Oasis Home Mortgages serves the northwest DFW corridor — Grapevine, Roanoke, Southlake, Westlake, Colleyville, Argyle, and Keller. Founder Shane Campbell brings 20+ years of mortgage experience and an approach built on borrower education rather than product pushing. With 166+ five-star Google reviews, the track record speaks for itself. Oasis offers broad lender access for competitive rates on both VA and conventional loans, plus specialized programs for first-time buyers, luxury home purchasers, and real estate investors. Learn more about their military mortgage benefits and veteran loan programs to see how VA financing works in practice.
National VA Lender (Example Profile)
Large national VA lenders offer automated underwriting and wide rate shopping for well-qualified borrowers. The trade-off: call-center service, limited local market knowledge, and potentially longer closing timelines. Best suited for borrowers relocating from outside DFW who need a lender with a broad geographic footprint.
Regional Conventional Specialist (Example Profile)
Regional lenders focused on conventional products often excel at down payment assistance programs, investor financing, and second-home loans. If you’re a non-veteran buyer or purchasing an investment property, their depth in conventional guidelines can be valuable. However, their VA loan expertise and funding fee transparency may be limited compared to a VA-specialist lender.
| Lender Type | Best For | Key Strengths | Considerations |
|---|---|---|---|
| Oasis Home Mortgages | Veterans, first-time buyers, luxury, investors in NW DFW | Local expertise, 166+ 5-star reviews, broad lender access, VA + conventional | Focused on DFW market; not a national call center |
| National VA Lender | Well-qualified borrowers relocating to DFW | Automated underwriting, wide rate shopping | Less local knowledge; potential closing delays |
| Regional Conventional Specialist | Non-veterans, investment property buyers | Deep conventional expertise, investor/second-home options | Limited VA offerings; may lack funding fee transparency |
Regulatory and Market Factors Affecting Your Choice in 2026
Texas adds a layer of complexity that every DFW homebuyer needs to understand, regardless of which loan type they choose. Under Texas Constitution Article XVI, Section 50, cash-out refinances for both VA and conventional loans are capped at 80% LTV, limited to once per 12-month period, and subject to strict fee limits. This applies equally whether you’re a veteran or a conventional borrower — so if you anticipate needing equity access later, factor this into your long-term strategy. You can explore cash-out refinance options to understand how these rules apply to your situation.
A significant change for veterans purchasing new construction: the VA eliminated its builder-ID requirement as of March 31, 2026 (VA Circular 26-25-1). Builders no longer need to be on a specific VA-approved list for standard new construction projects, removing a previous friction point. VA appraisal and Minimum Property Requirements still apply, but the process is meaningfully faster for veterans buying in new developments across Roanoke, Argyle, and other growth corridors in northwest DFW.
On the conventional side, conforming loan limits increased from 2024’s $766,550 baseline, reflecting continued home price appreciation across DFW. In Tarrant and Denton counties, where Trophy Club and surrounding communities sit, buyers approaching or exceeding conforming limits should evaluate whether a fixed-rate mortgage structure or a jumbo product makes more sense for their price point. Texas homestead exemptions reduce property tax burdens for primary residences — applicable to both VA and conventional borrowers — though Texas property taxes remain above the national average, and homeowners insurance costs are elevated due to severe weather exposure.
For buyers who may not qualify for VA or conventional financing due to income documentation challenges, non-QM loan programs offer alternative qualification pathways worth exploring alongside your primary options.
Why Choose Oasis Home Mortgages for Your VA or Conventional Loan in DFW
Choosing between a VA loan and a conventional loan is one of the most consequential financial decisions you’ll make as a homebuyer — and getting it right requires a lender who understands both products deeply, not one who defaults to whatever earns the highest commission. Oasis Home Mortgages, based in Trophy Club and serving Grapevine, Roanoke, Southlake, Westlake, Colleyville, Argyle, and Keller, was built around exactly that kind of honest, education-first approach.
Shane Campbell’s 20+ years of mortgage experience means he’s seen every market cycle and every loan scenario the northwest DFW corridor can produce — from first-time buyers navigating zero-down VA financing to luxury buyers optimizing a jumbo conventional structure. That depth of experience, combined with broad lender access for competitive rates on both VA and conventional loans, means Oasis can actually run the numbers for your specific situation rather than offering a generic recommendation.
The 166+ five-star Google reviews reflect something that’s hard to manufacture: a consistent track record of clients who felt informed, respected, and well-served through one of the most stressful purchases of their lives. Whether you’re a veteran evaluating your VA entitlement, a first-time buyer weighing down payment assistance programs, or an investor looking at portfolio loan options, Oasis brings the same personalized rigor to every file.
Get A Quote from Oasis Home Mortgages today and discover exactly how much you can save with the right financing strategy for your DFW home purchase.
Frequently Asked Questions
No — not for most borrowers. The VA Funding Fee is a one-time cost of 2.15% for first-time users with no down payment, and it can be financed into the loan rather than paid at closing. The long-term savings from avoiding monthly PMI — which runs $90–$485 per month on a $400,000 loan — far outweigh this fee over 5, 10, or 30 years. Over 10 years, PMI savings alone can total $10,800–$58,200, typically exceeding the financed funding fee by a wide margin. Additionally, disabled veterans and Purple Heart recipients are exempt from the funding fee entirely, making the VA loan an even clearer financial winner for those borrowers.
Historically, some sellers perceived VA offers as more complex or slower to close due to appraisal requirements. In today’s DFW market, however, informed real estate agents recognize that a pre-approved VA offer from a well-qualified veteran is strong and reliable. The recent elimination of the VA builder-ID requirement and the VA’s generous seller concession limits — up to 4% of the loan amount — make VA offers highly competitive, especially in markets like Trophy Club and Grapevine where educated sellers and their agents understand the strength of a government-backed guarantee. Working with an experienced local lender who can demonstrate a clean VA closing track record helps counter any remaining hesitation.
The VA itself does not set a minimum credit score, but most VA-approved lenders require 620–640 through their own lending overlays. Conventional loans also typically require a minimum of 620–640, with higher scores unlocking better rates and lower PMI costs. The meaningful difference is in how each loan type evaluates your overall financial picture: VA loans use a residual income analysis — measuring your discretionary income after major expenses based on family size and region — rather than a strict debt-to-income cap. This approach often provides more flexibility for veterans whose DTI might be slightly elevated but whose household cash flow is genuinely strong.
No — VA loans are restricted to primary residences only. If you want to purchase a second home, vacation property, or rental investment, you’ll need a conventional loan or another financing vehicle. That said, some veterans with remaining entitlement strategically use a conventional loan for a second property while preserving their VA benefit for a future primary residence purchase. Multi-unit properties (up to four units) are an exception: if you occupy one unit as your primary residence, VA financing can apply to the whole property, which can be a powerful wealth-building tool.
Oasis Home Mortgages combines 20+ years of mortgage expertise with 166+ five-star Google reviews and a Trophy Club location that puts them at the center of the northwest DFW corridor — serving Grapevine, Roanoke, Southlake, Westlake, Colleyville, Argyle, and Keller. Founder Shane Campbell’s deep local market knowledge means he understands the specific price dynamics, neighborhood nuances, and lender requirements that shape deals in this part of DFW. Broad lender access ensures competitive rates on both VA and conventional loans, and specialized programs for first-time buyers, luxury properties, and investors mean your specific situation receives tailored expertise — not a one-size-fits-all recommendation. Get A Quote today to see how Oasis can help you secure the best financing for your DFW home.
Ready to Compare VA and Conventional Loan Options in DFW?
Whether you’re a veteran ready to put your VA benefit to work or a conventional buyer optimizing your down payment strategy, the right loan can save you tens of thousands of dollars over the life of your mortgage. The team at Oasis Home Mortgages will run the real numbers for your specific situation — no pressure, no obligation. Get your personalized rate quote today and make your DFW home purchase with confidence.
Get A Quote*This article is for informational purposes only and does not constitute financial or legal advice. Rates, terms, and program eligibility are subject to change without notice. Equal Housing Opportunity. NMLS #1211817. Please contact us for personalized loan options.

